
7 min read · Last updated October 5, 2026
- A written dispute sent within 30 days forces a collector to stop collecting under 15 U.S.C. § 1692g(b), until it sends you proof of the debt.
- The three nationwide credit bureaus will not report an unpaid medical collection for the first 12 months, never report one under $500, and remove one entirely once it’s paid.
- If a No Surprises Act dispute already ruled in your favor and the provider still bills you, the federal No Surprises Help Desk takes a complaint directly.
- Calling the provider’s billing office and asking for an internal account recall works faster than disputing with the collection agency alone, because the provider can pull the account back at the source.
A medical bill can land in collections before your insurance company finishes reviewing the same claim, and federal law gives you a tool to freeze it the moment that happens. Under 15 U.S.C. § 1692g(b), a debt collector has to stop collecting as soon as you dispute the debt in writing.
Maria Delgado found this out three weeks after her son’s emergency-room stitches. Her insurer’s portal still showed the $1,840 claim as “in review” when a collection agency’s letter arrived demanding the full balance.
In this article
- Why a medical bill gets sent to collections before the claim
- The first 72 hours: get the explanation of benefits and dispute in writing
- Asking the provider to recall the account
- What actually happens to your credit report from here
- If a No Surprises Act dispute already went your way
Why a medical bill gets sent to collections before the claim
A hospital’s billing system and your insurer’s claims system do not share a clock. The provider submits a claim, then starts its own internal countdown toward an unpaid account, often 45 to 60 days. The insurer runs its own review on a separate schedule that can take just as long, especially on an emergency claim with extra documentation.
When the provider’s countdown finishes first, the account goes to collections while the insurer’s review is still open. The debt collector who receives it usually has no idea a claim is pending, because the hospital’s billing office and its outside collection agency rarely share real-time claim status.
This is why a fully covered bill, or one where you only owe a small copay, can show up as a collections notice for the entire balance. The collector is working from the provider’s own ledger, not your insurer’s determination.
The first 72 hours: get the explanation of benefits and dispute in writing
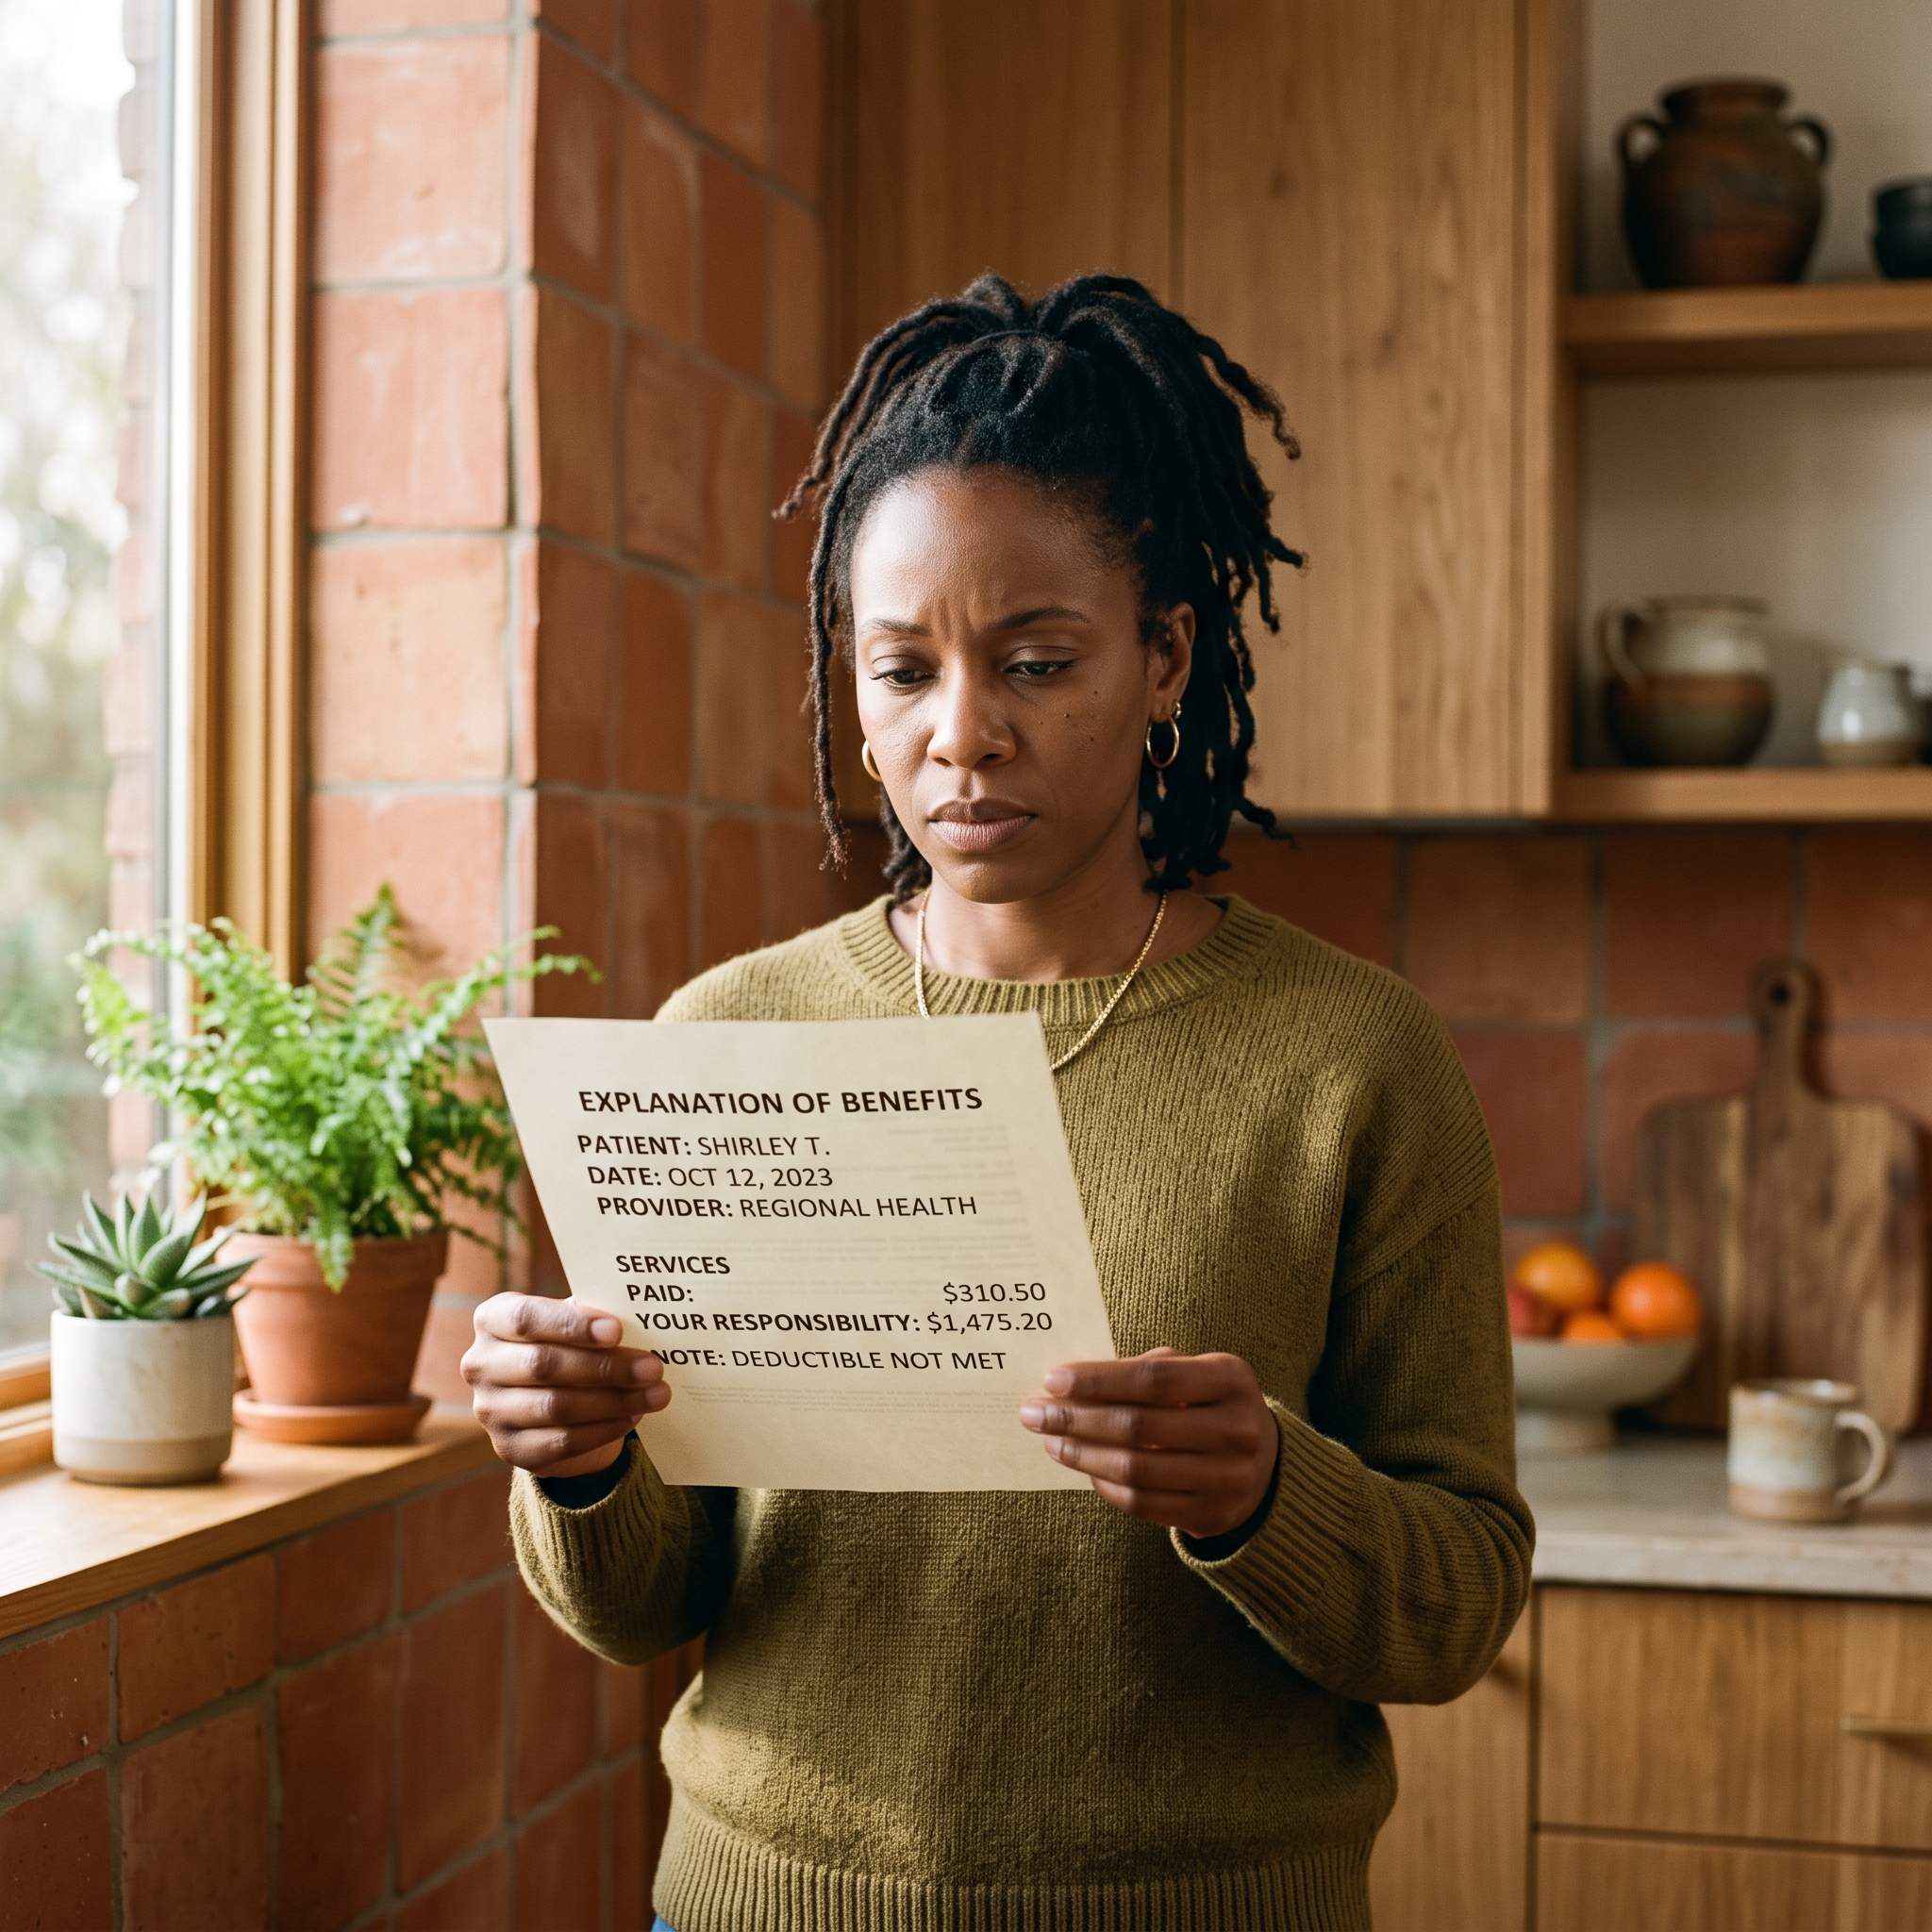
Call your insurer first and ask for the explanation of benefits (EOB) for that exact date of service. The EOB states what the plan has approved, what it still owes the provider, and what portion, if any, is genuinely your responsibility.
Maria’s EOB confirmed her plan owed $1,690 of the $1,840 bill, leaving her with a $150 copay, the same figure the hospital had quoted at check-in. The collector had been pursuing the full balance.
Once you have that EOB, send the collector a written dispute by certified mail within 30 days of its first contact, referencing the specific bill and attaching a copy of the EOB.
Under 15 U.S.C. § 1692g(b), that written dispute forces the collector to cease collection activity until it mails you verification of the debt. A phone call does not carry the same legal weight; only a written dispute starts that clock.
Keep a copy of the letter and the certified-mail receipt. If the collector calls or reports the account anyway after receiving your dispute, that is itself a potential violation you can raise with the Consumer Financial Protection Bureau (CFPB), the federal agency that oversees debt collectors. The same certified-mail approach works for disputing a collection letter on a non-medical account that has already moved to an outside agency.
Asking the provider to recall the account
A written dispute to the collector buys you time, but it does not erase the bill. The faster fix is often a direct call to the hospital or provider’s own billing office, not the outside agency.
Ask specifically for an internal account recall: a request that the provider pull the account back from the collection agency because the insurance claim is still active. Reference the claim number and the date your insurer confirmed it was under review. Billing offices can issue a recall because they, not the collection agency, own the underlying account and can instruct the agency to stop work on it.
Follow up in writing, even a short email, so there is a record that you made the request and the date you made it. If the provider agrees to recall the account, ask for written confirmation and keep it with your other records in case the collection agency’s system lags behind the provider’s.
If the account already carries an unexplained charge, pair the recall request with an itemized bill and a formal billing dispute, since a provider is far more likely to recall an account once it sees a documented error on the same bill.
What actually happens to your credit report from here
Even if the bill sits unresolved for a while, the three nationwide credit bureaus changed how they handle medical collections starting in 2022. An unpaid medical collection will not appear on your credit report for the first 12 months after it is placed, which gives the insurance review time to finish before it can touch your score at all.
| Balance and status | Does it appear on your credit report? |
|---|---|
| Any amount, under 12 months old | No, regardless of balance |
| Under $500, any age | No, never reported |
| $500 or more, unpaid, over 12 months old | Yes, eligible to report |
| Any amount, paid in full | No, removed once paid |
That table is why resolving the claim before the 12-month mark matters more than winning a fast fight with the collector. If Maria’s insurer finishes its review and pays the $1,690 within that window, the account never has to touch her credit at all, whether or not the collector has been disputed.
A federal rule that would have banned medical debt from credit reports entirely was finalized in January 2025, but a federal court vacated it in July 2025. The bureau policy in the table above is what currently governs, not that vacated rule.
If a No Surprises Act dispute already went your way
Some of these bills involve a separate federal protection: the No Surprises Act, which limits what certain out-of-network and emergency providers can bill you directly. If you already won a dispute under that law and the provider is still billing you, or sent the account to collections anyway, the federal government has a specific channel for exactly that complaint.
The Centers for Medicare & Medicaid Services (CMS) runs the No Surprises Help Desk for this purpose. Its own guidance on disputing a medical bill states plainly that if “a dispute was decided in my favor, but the provider is still billing me or sent my bill to collections,” the next step is to submit a complaint to the Help Desk directly, and CMS will review the situation and outline next steps.
Frequently asked questions
Can a medical bill go to collections if I have insurance? Yes. Providers often send an account to collections based on their own billing timeline, regardless of whether your insurer has finished processing the claim. Having insurance does not pause the provider’s internal collections clock.
Does disputing a medical bill in writing actually stop collection calls? A written dispute sent within 30 days of the collector’s first contact forces it to stop collecting under 15 U.S.C. § 1692g(b) until it sends you proof of the debt. A verbal dispute during a phone call does not carry the same legal protection.
How long before an unpaid medical bill shows up on my credit report? The three nationwide credit bureaus will not report it for the first 12 months after it goes to collections, and never report a balance under $500 at all. A paid medical collection is removed from your report regardless of amount.
What if the hospital already sent my account to an outside agency? You can still ask the provider’s billing office to issue an internal recall, pulling the account back from the agency because your insurance claim is still open. The provider, not the agency, controls that decision.
Can a bill be pulled back from collections once it’s already there? Yes, if the provider agrees to recall it, or if your insurer resolves the claim and pays the balance before it is reported. Get any recall agreement in writing and keep your certified-mail receipt for the dispute letter.